5 Year Term Loan $135,000 Just Funded in New Mexico!
The Deal At A Glance
- Amount$135,000
- Product5 Year Term Loan
- StructureUnsecured
- Term5 Years
- LocationNew Mexico
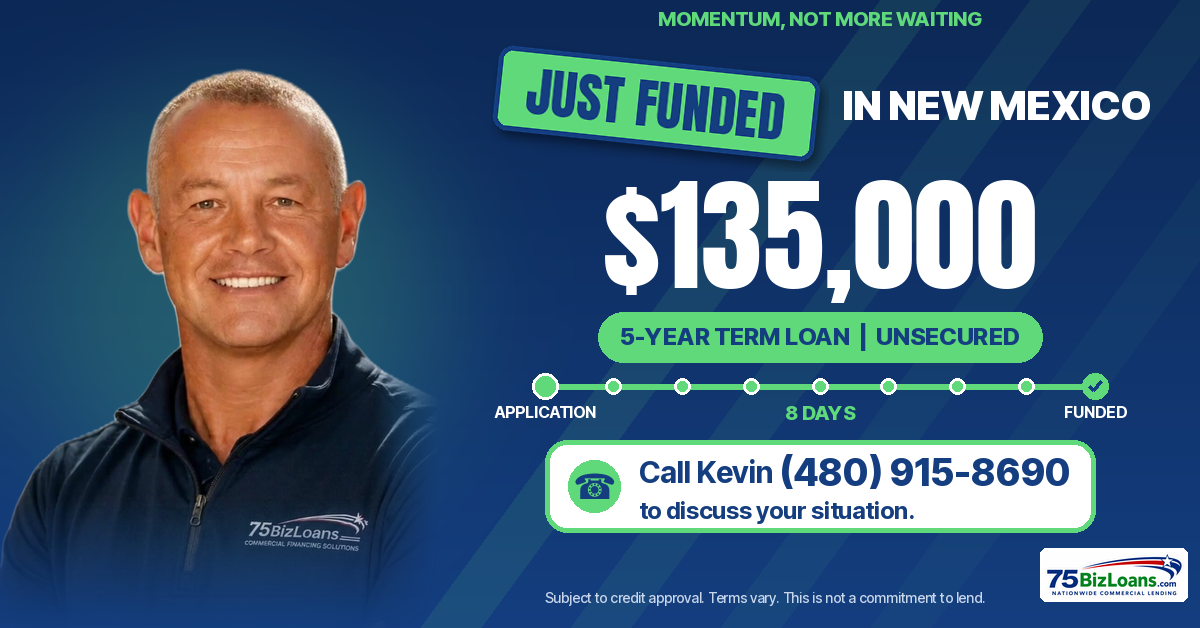
I just funded a 5 year term loan for $135,000 in New Mexico, and the owner now has one fixed payment to plan around. Results vary; every file is different; no approval is guaranteed. I am sharing it because I know the feeling that comes before a deal like this one… the knot in your stomach when the account is thinner than the plan, and the quiet fear that the bank will make you wait until the opportunity is gone. If a search for albuquerque business loans brought you here, keep reading. This is what a 5 year term loan can look like when the file is built right and placed with the right capital source.
Here is the short version. A 5 year term loan gives a business owner a lump sum up front and five years to pay it back on a set schedule. This one was unsecured, so no building or equipment was pledged as collateral. I work with 200+ capital partners and place financing up to $100 million nationwide, but some of the deals I am proudest of are the ones that change the month for an owner. A 5 year term loan of $135,000 is exactly that kind of deal. Don’t Beg the Bank!
The Weight You Carry Before the Money Lands
If you run a business, you know the math that keeps you up at night. Payroll is coming whether the receivables show up or not. A supplier wants a deposit. A growth window opens and closes in weeks, not quarters. You have built something real, and you still feel like you are asking permission to grow it.
Then comes the bank. The forms, the waiting, the questions that make you feel like a suspect instead of an owner. Banks hand out umbrellas when the sun is shining, not when you are weathering the storm. Too many owners I talk to have heard a slow no, or worse, a maybe that drags on until the moment passes. That is the pain I hear on almost every call, and it is why I do this work.
I am not going to share this owner’s story or file. That stays private. What I can share is how a 5 year term loan works, why I like the structure, and what you can do if you are carrying the same weight right now.
Why I Placed This as a 5 Year Term Loan
When an owner needs a meaningful lump sum and wants a payment they can plan around, a 5 year term loan is one of the first structures I look at. Five years spreads the payback out far enough to keep the monthly payment reasonable, but short enough that the debt does not hang around forever. It is clean. You know what you owe, you know when it ends, and you can build a budget around it.
Compared with short-term options that pull from your account daily or weekly, a 5 year term loan gives you breathing room. Compared with a revolving line, it gives you a fixed finish line. That combination of room and discipline is why a 5 year term loan fits so many owners who are tired of patching cash flow with expensive short money. You can see the full program on my unsecured business loans page.
A 5 year term loan is not the answer for everyone. If you need to draw and repay over and over, a business line of credit may fit better. If you need machinery, equipment financing lets the equipment carry the deal. My job is to match the money to the mission, not to push one product.
What an Unsecured Term Loan Really Means
An unsecured term loan is approved on you and your business, not on a piece of property pledged as collateral. There is no building to appraise, no lien on your equipment, and no down payment. That is a big part of why this structure can move without the weeks of property work a real estate deal needs. The tradeoff is that the program looks hard at credit and income, so the file has to be strong on paper.
This deal was a 5 year term loan with no collateral. For many owners, that is a huge relief. Your home and your building are not on the line in the way they would be with a secured deal. If you want to see how I handle property-backed financing instead, my commercial real estate loan programs cover the secured side.
How This Deal Came Together
Results vary; every file is different; no approval is guaranteed. That number describes this deal only, and I will never promise it on yours. For this program, Business loans are normally approved in 4 hours to 3 days once your application and all documents are in., and some files take longer.
What I can tell you is what helps a 5 year term loan move. Clean documents, clear answers, and an owner who knows what the money is for. When I get those three things, I can put the file in front of the right capital source the first time instead of shopping it around. A smooth deal is mostly preparation, not luck.
When the funding hit, the feeling on the other end is the reason I keep doing this. Relief first. Then pride. The owner did the work to build a fundable business, and now that business has the capital to take its next step. Don’t Beg the Bank!
Albuquerque Business Loans and the Rest of New Mexico
Albuquerque business loans are a big part of the calls I take from New Mexico, simply because so many of the state’s owners operate in and around the metro. Rio Rancho, the South Valley, the Northeast Heights, and the West Side all have owners who need capital to hire, stock up, or expand. A 5 year term loan works the same way for all of them.
The state is much bigger than one metro, though. Las Cruces, Santa Fe, Farmington, Roswell, Hobbs, Clovis, and the smaller towns in between all have businesses that keep their communities running. If you own one of them, the playbook does not change. I look at the business, the owner, and the goal, and I go find the money.
New Mexico owners who also hold property can talk to me about the secured side too. My New Mexico commercial real estate loans page covers buildings, cash-out, and purchase money across the state.
Is a Small Business Term Loan Right for You?
A small business term loan makes the most sense when you can name what the money will do. Hiring ahead of a busy season. Buying inventory at a better price. Paying off expensive short-term debt that is eating your margin. Opening a second location. The clearer the purpose, the easier it is to see whether a five-year payback fits.
It is usually the wrong move when the money would just cover a hole that keeps coming back. In that case, I would rather talk through working capital options or the cash flow problem underneath, so you are not stacking debt on a leak. I would rather lose a deal than put an owner in the wrong loan.
Signs a five-year payback fits
Your revenue is steady enough to carry a set monthly payment. The investment will keep paying you back for years, not weeks. You want to stop renewing short-term advances. And you would rather know exactly when the debt ends than carry a balance with no finish line.
New Mexico Business Loans Without Begging the Bank
New Mexico business loans do not have to start and end at one bank branch. I work with 200+ capital partners, so when one says no or moves too slowly, I am not stuck. I take your file to a capital source that actually wants your kind of deal. That is the whole idea behind Don’t Beg the Bank! You built the business. You should not have to grovel for access to capital.
The Federal Reserve Small Business Credit Survey tracks how small firms apply for financing and how often they come up short. If you have felt that squeeze, you are not alone, and it is not a verdict on your business. It is a reason to work with someone who has more than one door to knock on. Government-backed options are worth knowing too, and the U.S. Small Business Administration loan programs page lays out how those programs work.
What a 5 Year Term Loan Does for Your Cash Flow
Here is the part owners feel in their gut. A 5 year term loan turns one big, scary number into a payment you can see coming. Instead of watching an advance pull money out of your account every day, you plan around one known amount. That predictability is worth a lot when you are the one signing the paychecks.
It also changes how you make decisions. With a 5 year term loan in place, you stop asking whether you can survive the month and start asking what the money can build. You can negotiate with suppliers from strength, hire the person you have been putting off, or finally fix the thing that slows your team down every single day.
And because the debt has an end date, you can see the finish line from day one. Five years from funding, a 5 year term loan is simply done. No renewals, no balance that never moves. Just a business that used the capital and kept the gains.
Questions I Ask Before I Recommend a 5 Year Term Loan
Before I suggest a 5 year term loan to anyone, I ask a few honest questions. What exactly will the money do? How will it pay you back? Can your current revenue carry the payment if the next few months are slow? And is there a cheaper or better-fitting program you should look at first?
If the answers line up, a 5 year term loan can be one of the cleanest tools in the box. If they do not, I will tell you, and I will show you another path. That honesty is how I have built a business on referrals instead of pressure. It is also how I sleep at night.
Other Ways I Fund New Mexico Owners
A 5 year term loan is one tool. Here are the programs I place most often for business owners, each with its own page:
If you own investment property, my investment property loans and bridge loans may fit better than an unsecured deal. For the full menu, browse all of my loan programs.
What the 5 Year Term Loan Program Looks For
I like to be straight about the bar so nobody wastes time. The term loan program I place typically covers amounts from $50,000 to $500,000. It generally looks for 680+ FICO scores on all 3 bureaus and your last 2 years personal tax returns. There is no collateral and no down payment.
Unsecured Term Loan up to $500,000: Apply now
Those are program guidelines, not a checklist this particular owner was measured against, and I am not sharing any detail of this borrower’s file. Every lender makes its own decision. If you are close on one item and strong on the others, call me anyway. I will tell you honestly where you stand and what I would fix first.
Why Owners Call Me Instead of Waiting on a Bank
A bank has one box. If your business does not fit it, you wait, you get a vague answer, or you get a no. I have 200+ capital partners behind me, and I know which ones want which kinds of deals. That means less guessing and fewer wasted weeks for you.
I also speak plainly. If a 5 year term loan is not the right fit, I will say so and point you to something that is. I get paid by the lender at closing. I would rather earn a referral than force a deal. Don’t Beg the Bank!
How I Work a 5 Year Term Loan File, Step by Step
First, I listen. You tell me what the money is for, how much you need, and what your business looks like today. In one call I can usually tell you whether a 5 year term loan is worth pursuing or whether another program fits better.
Second, I gather the documents the program needs, including your personal tax returns and basic business information, and I review them before anything goes out. A clean file is the single biggest thing that keeps a deal moving.
Third, I place the file with the capital source that fits it best. When an offer comes back, I walk you through it in plain English so you know exactly what you are signing. Then the lender funds, and you get to work.
The Relief on the Other Side
Every owner I talk to remembers the moment the money lands. The shoulders drop. The plan that lived on a napkin becomes a plan with a budget. The fear of not making it turns into the pressure of growing, which is a much better problem to have.
That is what this $135,000 means to me. Not a number on a screen, but an owner in New Mexico who gets to stop surviving and start building. If you want that feeling for your own business, the first step is a phone call.
Common Questions About a 5 Year Term Loan
What is a 5 year term loan?
A 5 year term loan is a lump sum of capital you repay on a set schedule over five years. You get the money up front, you know your payment, and you know exactly when the debt ends. On this deal I funded a $135,000 5 year term loan in New Mexico.
How long does a 5 year term loan take to fund?
Every file is different. Results vary; every file is different; no approval is guaranteed. For this program, Business loans are normally approved in 4 hours to 3 days once your application and all documents are in.
What does a 5 year term loan cost to set up with you?
I get paid by the lender at closing. Your exact terms depend on your credit, your income, and the lender, and I walk you through every number before you sign anything.
Do I need collateral for an unsecured term loan?
No. An unsecured term loan is approved on your credit and income instead of property. There is no building to appraise and no lien on your equipment, which is a big reason owners like this structure.
Who qualifies for an unsecured term loan?
The unsecured term loan program I place generally looks for 680+ FICO scores on all 3 bureaus and your last 2 years personal tax returns. Every lender makes its own decision, so call me and I will tell you honestly where you stand.
Do you handle albuquerque business loans?
Yes. Albuquerque business loans are a big share of my New Mexico calls, from Rio Rancho to the Northeast Heights to the West Side. I work with 200+ capital partners, so I can match an Albuquerque owner with a capital source that fits the deal.
Why call you for albuquerque business loans instead of a local bank?
A bank has one box. When you call me about albuquerque business loans, I can take your file to the lenders that actually want your kind of deal. That means fewer wasted weeks and a straight answer. Don’t Beg the Bank!
What can I use a small business term loan for?
A small business term loan works best for a clear purpose: hiring, inventory, expansion, a new location, or paying off expensive short-term debt. The investment should keep paying you back over the life of the loan.
Is a small business term loan better than a line of credit?
It depends on how you use money. A small business term loan gives you one lump sum and a fixed finish line. A line of credit lets you draw and repay over and over. I will help you pick the one that fits your cash flow.
How big are the new mexico business loans you arrange?
I place new mexico business loans and financing nationwide up to $100 million across 200+ capital partners. Each program has its own range. My term loan program typically runs from $50,000 to $500,000.
Can new mexico business loans close outside Albuquerque?
Absolutely. I arrange new mexico business loans statewide, including Las Cruces, Santa Fe, Farmington, Roswell, Hobbs, and Clovis. The process is the same wherever your business operates.
Meet Kevin Kermeen
I’m Kevin Kermeen, a nationwide commercial loan broker with 20+ years in the arena and more than $500 million funded. I work with 200+ capital partners and arrange financing up to $100 million. I do not work for a bank… I work for you. Call me and I will tell you straight whether a 5 year term loan fits your business. Don’t Beg the Bank!
Call Kevin (480) 915-8690 to discuss your situationYour Next Move Starts With One Call. Don’t Beg the Bank!
Tell me what the money is for and what your business looks like today. I will tell you straight whether a 5 year term loan or another program fits, and I will not waste your time if it does not. I get paid by the lender at closing.
Call Kevin (480) 915-8690 to discuss your situation7 DAYS A WEEK · ARIZONA TIME | Or send me your deal here | See more Just Funded deals | 75BizLoans.com
Subject to credit approval. Terms vary. This is not a commitment to lend.
Apply for funding · Call Kevin (480) 915-8690 to discuss your situation, 7 days a week (Arizona Time).
Explore the program hub: Unsecured Term Loan. Call Kevin (480) 915-8690 to discuss your situation, 7 days a week (Arizona Time).
Want my funding tips first in Google? Add 75BizLoans as a preferred source.